The Ultimate Guide to Travel Insurance: What's Covered and What Isn't
09 July 2026
Booking a flight and hotel is exciting, but securing travel insurance is what gives you genuine peace of mind. Whether you are traveling for a crucial corporate conference or a long-awaited family vacation, unexpected events can turn a dream trip into a costly nightmare.
However, one of the biggest mistakes travelers make is assuming that a standard travel insurance policy covers everything. Policies are essentially legal contracts, and understanding the fine print is vital to ensuring you aren't left stranded abroad with a denied claim.
To help you navigate your options, Valiant Business Solutions (VBS) has broken down exactly what standard travel insurance typically covers, the common exclusions you need to watch out for, and how to bridge the gap with optional upgrades.
1. The Essentials: What Travel Insurance Actually Covers
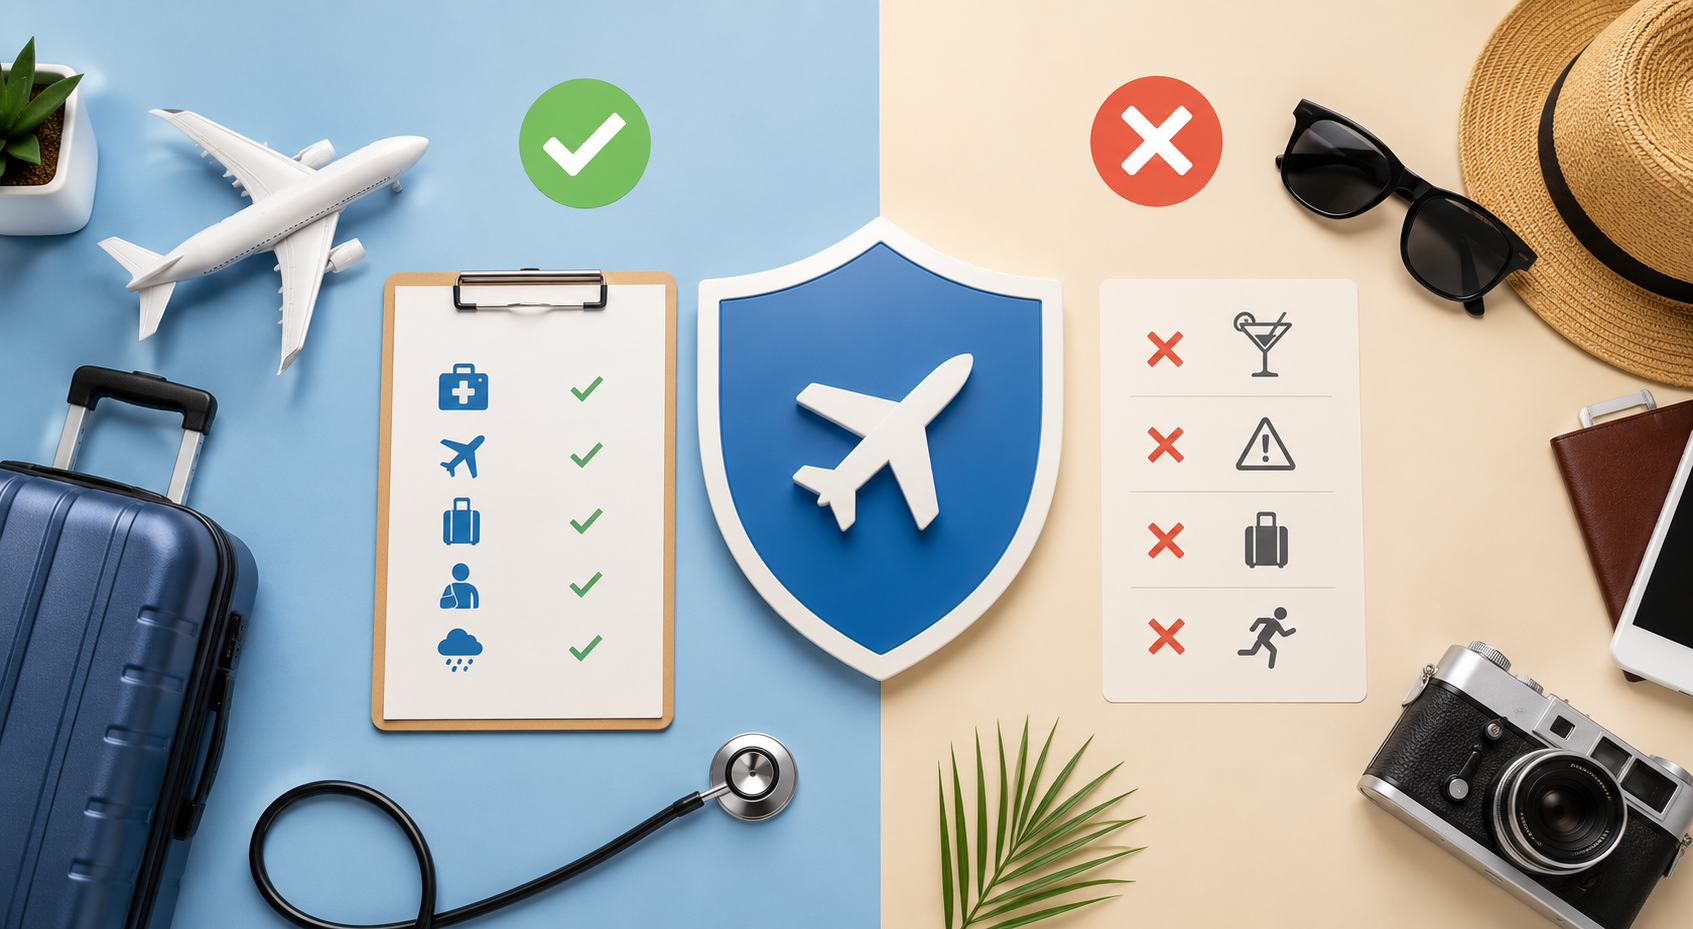
While policies vary by provider, a comprehensive standard travel insurance plan generally protects you against unforeseen, unavoidable events. Key coverages include:
- Trip Cancellation & Interruption: Reimburses you for prepaid, non-refundable expenses if you must cancel or cut your trip short due to covered reasons (e.g., sudden illness, injury, death of an immediate family member, or a sudden natural disaster at your destination).
- Emergency Medical Expenses: Arguably the most important benefit. It covers doctor visits, hospital stays, and emergency dental care if you suffer a sudden illness or injury while abroad. (Note: Your domestic health insurance often provides zero coverage overseas).
- Emergency Medical Evacuation: If you are severely injured in a remote area, this covers the exorbitant cost of airlifting or transporting you to the nearest adequate medical facility, or even back to your home country.
- Baggage Loss and Delay: Provides reimbursement for personal items if your luggage is lost, stolen, or damaged. It also offers an allowance to buy essential clothes and toiletries if your bags are delayed by the airline for a specified amount of time (usually 12-24 hours).
- Travel Delay: Reimburses you for meals, accommodation, and transportation if your flight is delayed for a covered reason (like severe weather or airline mechanical issues) beyond a certain timeframe.
2. The Exclusions: What Your Policy Won't Cover
Insurance is designed to cover the unexpected. Consequently, claims are frequently denied when the situation falls under standard policy exclusions. Here is what is typically not covered:
- Pre-Existing Medical Conditions: Standard policies will not cover care for a medical condition you had before buying the policy. If you have asthma and suffer an attack on your trip, standard coverage won't apply.
- "Changing Your Mind" or Fear of Travel: Standard trip cancellation does not cover you if you simply decide not to go, break up with your travel partner, or feel nervous about a geopolitical event in the destination country.
- Reckless Behavior and Intoxication: If you are injured while under the influence of alcohol or non-prescription drugs, or while acting recklessly, your medical claim will be denied.
- High-Risk and Adventure Sports: Scuba diving, skydiving, bungee jumping, and even standard winter sports like skiing are often explicitly excluded from basic medical coverage due to their high injury rates.
- Foreseeable Events: If you buy a policy after a hurricane has been officially named or a major strike has been announced, you cannot claim trip cancellation for those specific events. They are no longer "unforeseen."
VBS Insight: Never try to hide a pre-existing condition from your insurer. If you need medical attention abroad, insurers will review your home medical records. If they find an undeclared condition, they will void your coverage entirely.
3. Optional Upgrades to Bridge the Gap
If your itinerary includes activities or circumstances that fall outside standard coverage, you can usually purchase riders or upgrades to protect yourself:
- Cancel For Any Reason (CFAR): This premium upgrade allows you to cancel your trip for absolutely any reason (including fear or changing your mind) and receive a partial refund (usually 50% to 75% of your costs). You typically must buy CFAR within 14-21 days of making your first trip deposit.
- Adventure Sports Rider: An add-on that extends your medical and evacuation coverage to include high-risk activities like mountaineering, scuba diving, or zip-lining.
- Pre-Existing Condition Waiver: Many providers will waive the pre-existing condition exclusion if you purchase your insurance shortly after booking your trip (usually within 14 days) and are medically cleared to travel on the day you buy the policy.
4. How Valiant Business Solutions Protects Your Journey
Reading pages of insurance jargon is nobody's idea of a good time. At VBS, our Travel Insurance Experts ensure you get exactly the coverage you need without paying for what you don't.
Whether you are organizing a massive corporate MICE event or planning a solo business trip, we partner with top-tier global insurers to provide customized coverage. We help you navigate the nuances of medical waivers, high-value electronics coverage, and complex international claim processes.
Travel with Confidence Today
Don't let unforeseen circumstances derail your itinerary or your budget.
Understanding your policy is the first step toward smart, safe travel.
Ready to secure your next trip? Contact
Valiant Business Solutions today to find the perfect
travel insurance plan for your needs.
Frequently Asked Questions About Travel Insurance
Typically, standard policies exclude pre-existing conditions. However, many providers offer a 'Pre-Existing Medical Condition Exclusion Waiver' if you purchase the insurance shortly after making your first trip deposit and are medically cleared to travel at the time of purchase.
No. Standard trip cancellation only covers specific, documented reasons (like illness, death in the family, or natural disasters). If you want the flexibility to cancel for any reason, you must purchase a 'Cancel For Any Reason' (CFAR) upgrade.
Most basic policies consider activities like scuba diving, bungee jumping, and skiing as 'high-risk' and exclude them. You will need to purchase an 'Adventure Sports Rider' or a specialized policy to ensure you are covered during these activities.
VBS partners with top-tier insurance providers to offer comprehensive, tailored plans for corporate and leisure travelers. We help you navigate the fine print, ensure you have the right coverage for your specific destination and itinerary, and assist you if you ever need to file a claim.